Protect The Ones You Love With Life Insurance
Contact Denis Doulgeropoulos of Omega Investments & Insurance Today
PROTECT WHAT MATTERS MOST TODAY AND ALWAYS.
The saying goes that life doesn’t give you anything you can’t handle. However, it doesn’t mean you have to handle it alone. Having a financial professional by your side is more important than ever today; someone who can help you evaluate your needs, assess the current economic landscape, and recommend a plan of action that will help protect your wealth, lifestyle, and dreams for the future. The time is now – let’s get started.
Licensed to assist with:
Orange County Life Insurance, Long-term Care, Disability Insurance & Annuities
Orange County Life Insurance & Planning
Who Denis Doulgeropoulos Serves in Orange County
Denis Doulgeropoulos is an Orange County life insurance agent and financial professional with Omega Investments, based in Irvine, California. Denis works with individuals, families, business owners, executives, entrepreneurs, and professionals throughout Orange County who want to protect their income, families, businesses, and long-term financial future.
Business Owners
Denis helps Orange County business owners protect the companies they have built. Strategies include key person insurance, buy-sell agreement funding, business succession planning, and executive benefits designed to provide liquidity and continuity if an owner or key employee dies unexpectedly.
Executives & Professionals
Denis works with physicians, attorneys, executives, and entrepreneurs whose income, business interests, real estate, and family obligations call for more than a basic policy. When appropriate, he coordinates insurance strategies with your attorney, CPA, and other advisors.
Families & High-Net-Worth
Life insurance is about protecting the people who depend on you. Denis helps Orange County individuals and families evaluate how much coverage they may need and which type fits their goals, from income replacement and mortgage protection to legacy planning and long-term family wealth protection.
For Individuals & Families
Life Insurance for Orange County Families
Life insurance is about protecting the people who depend on you financially. Denis helps individuals and families evaluate how much life insurance they may need and determine which type of coverage is appropriate for their goals.
Life insurance planning may be used to help provide funds for:
- Income replacement for a surviving spouse or family
- Mortgage and other debt obligations
- Children’s education
- Final expenses
- Estate and legacy planning
- Supplemental retirement strategies
- Long-term family wealth protection
Denis offers access to several types of life insurance, including term life insurance, whole life insurance, permanent life insurance, and universal life insurance. The appropriate type and amount of coverage depend on the client’s financial situation, objectives, health, age, and long-term goals.
For Business Owners & Entrepreneurs
Life Insurance for Orange County Business Owners
Denis also works extensively with business owners and entrepreneurs who need more sophisticated insurance and financial-planning strategies. Business life insurance can play an important role in protecting a company when an owner, partner, executive, or other key person dies unexpectedly. Strategies may include:
Key Person Life Insurance
Helps businesses protect themselves against the financial consequences associated with the death of an owner, executive, rainmaker, or other individual who is critical to the company’s success.
Buy-Sell Agreement Funding
Life insurance can provide liquidity to help fund the purchase of a deceased owner’s business interest and facilitate an orderly transfer of ownership.
Business Succession Planning
Denis works with business owners to help develop strategies for transferring a company to partners, family members, employees, or future owners.
Executive Benefits and Retention Strategies
Life insurance and other financial products may be incorporated into strategies designed to attract, retain, and reward important employees and executives.
Permanent Protection
Whole Life and Cash Value Life Insurance
For clients interested in permanent protection, Denis offers whole life and other cash value life insurance strategies.
Permanent life insurance can provide a death benefit while potentially accumulating cash value over time. Depending upon the policy, properly structured cash value may provide a source of liquidity that a policy owner can access through withdrawals or policy loans.
Denis helps clients understand the differences between term life insurance, whole life insurance, universal life insurance, and other permanent life insurance strategies so they can make informed decisions based on their objectives.
Death Benefit
Cash Value
Liquidity Options
Beyond the Policy
Retirement and Wealth Protection
Insurance planning is often only one component of a client’s overall financial strategy. Denis works with clients who are preparing for retirement, accumulating assets, protecting income, or looking for ways to create a more predictable financial future.
Services can include:
- Retirement planning
- Annuities
- Life insurance planning
- Cash value accumulation strategies
- Long-term care planning
- Disability income protection
- Estate and legacy planning
- Business succession planning
- Key person insurance
- Buy-sell planning
Advanced Planning
Life Insurance for High-Income Professionals and Executives
Denis works with physicians, attorneys, executives, entrepreneurs, real estate professionals, and other high-income individuals whose financial circumstances may require more advanced insurance planning.
These clients may have significant income, business interests, real estate, retirement assets, or family obligations that cannot always be addressed adequately with a basic life insurance policy.
Denis can coordinate insurance strategies with a client’s existing attorneys, CPAs, tax professionals, and other advisors when appropriate.
Areas Served
Serving Orange County, California
From his Irvine office, Denis serves clients throughout Orange County, including these communities and surrounding Orange County areas:
- Irvine
- Newport Beach
- Laguna Beach
- Laguna Niguel
- Costa Mesa
- Huntington Beach
- Tustin
- Orange
- Mission Viejo
- Lake Forest
- Dana Point
- San Clemente
- San Juan Capistrano
- Coto de Caza
- Rancho Santa Margarita
- Anaheim
- Fullerton
- Yorba Linda
Whether you are looking for a life insurance agent in Orange County, comparing term vs. whole life insurance, considering cash value life insurance, protecting a business with key person insurance, funding a buy-sell agreement, or developing a comprehensive retirement and legacy strategy, Denis Doulgeropoulos can help you evaluate your options and develop a strategy around your financial objectives.
Meet Your Advisor
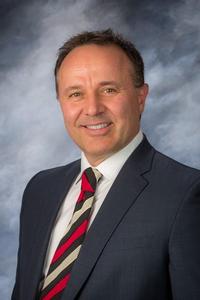
Denis Doulgeropoulos | Orange County Life Insurance Agent
Denis Doulgeropoulos is a licensed life insurance agent and financial professional with Omega Investments in Irvine, California. He helps Orange County families, professionals, executives, entrepreneurs, and business owners evaluate life insurance and financial strategies designed to protect the people, businesses, and assets that matter most.
Services include life insurance, term life insurance, whole life insurance, permanent life insurance, cash value life insurance, key person insurance, buy-sell planning, business succession planning, long-term care insurance, disability insurance, annuities, retirement planning, and estate and legacy strategies.

Common Questions
Frequently Asked Questions
Straight answers to the questions Orange County families, professionals and business owners ask most about life insurance.
Still have questions?
Talk with Denis directly about your family, business or retirement goals.
What type of life insurance should I get?
When it comes to life insurance, it’s always a good idea to consult with a professional life insurance agent who can understand your unique circumstances and guide you towards the most suitable policy. An agent can provide personalized advice and help you navigate the various options available, ensuring you make an informed decision.
Here are a few reasons why speaking with a life insurance agent is beneficial:
- Expertise and Knowledge: Life insurance can be complex, with different types of policies and varying coverage options. A knowledgeable agent can explain the intricacies, clarify any doubts, and provide you with the information you need to make an educated choice.
- Tailored Recommendations: Everyone’s financial situation and needs are different. An agent can assess your specific circumstances, including your age, marital status, dependents, and financial goals. By understanding your unique situation, an agent can recommend a policy that suits you best, providing the right coverage and benefits.
- Comprehensive Coverage Evaluation: Life insurance agents have experience in evaluating insurance coverage needs. They can assess your existing policies, if any, and determine if they align with your current circumstances. If necessary, they can recommend adjustments or additional coverage to ensure you have comprehensive protection for yourself and your loved ones.
- Access to Multiple Insurance Companies: An agent typically works with multiple insurance carriers, giving them access to a wide range of products and options. They can compare policies from different companies, considering factors like financial stability, policy features, and pricing. This allows you to explore multiple choices and select the most suitable one.
- Personalized Support and Guidance: By working with a life insurance agent, you benefit from ongoing support throughout the entire process. They can assist you in completing paperwork, answer your questions, and provide ongoing policy management. Additionally, if you ever need to make changes or update your coverage, your agent will be there to help.
The First Step Toward Financial Peace of Mind
Remember, life insurance is a crucial aspect of financial planning, providing protection and peace of mind for you and your loved ones. By engaging with a life insurance agent, you can ensure that you’re making an informed decision and choosing the policy that meets your specific needs. So, reach out to a professional agent today to discuss your options and take the first step toward securing your financial future.
At what age should you get life insurance?
The ideal age to get life insurance can vary depending on your individual circumstances and financial goals. However, there are a few key factors to consider when determining when to obtain life insurance coverage.
1. Dependents: If you have dependents such as children, a spouse, or older parents who rely on your income, it’s generally advisable to consider life insurance as soon as possible. This ensures that your loved ones will be financially protected in the event of your untimely passing.
2. Debt and Financial Obligations: If you have outstanding debts, such as a mortgage, student loans, or credit card debt, life insurance can help cover those obligations and prevent your loved ones from inheriting the financial burden. Starting early can allow you to secure coverage at a lower premium, especially if you’re in good health.
3. Affordability: Life insurance premiums are generally more affordable when you’re younger and in good health. As you age, the risk of health issues increases, which can lead to higher premiums or even the possibility of being denied coverage. By getting life insurance at a younger age, you can often lock in lower rates and potentially save money over the long term.
4. Future Insurability: It’s important to consider your future insurability when determining the right time to get life insurance. If you anticipate health issues or lifestyle changes that could impact your ability to obtain coverage in the future, it may be wise to secure a policy sooner rather than later.
Is it worth investing in life insurance?
Investing in life insurance can be a wise decision for many individuals and families, as it provides valuable financial protection and peace of mind. Here are a few reasons why life insurance is often considered worth the investment:
Financial Security for Your Loved Ones:
Life insurance ensures that your loved ones are financially protected in the event of your passing. It can provide a death benefit to cover expenses such as funeral costs, outstanding debts, mortgage payments, and everyday living expenses. This financial support can help your family maintain their lifestyle and achieve their long-term goals.
Income Replacement:
If you are the primary breadwinner in your family, life insurance can help replace the income that would be lost if something were to happen to you. This can provide stability and support for your dependents, ensuring they have the means to meet their financial obligations and pursue their dreams.
Paying Off Debts:
Life insurance can be used to pay off any outstanding debts you may have, such as a mortgage, car loan, or credit card debt. This prevents your loved ones from being burdened with these financial obligations after your passing.
Estate Planning:
Life insurance can play a significant role in estate planning. It can provide liquidity to cover estate taxes or other expenses associated with transferring assets to your beneficiaries. This helps preserve your estate and ensures that your loved ones receive their intended inheritance.
Business Continuation:
If you own a business, life insurance can be crucial for its continuity. It can provide funds to cover expenses, pay off business debts, and facilitate the smooth transition of ownership in the event of your passing. This protects your business partners, employees, and family members who rely on the business’s income.
Cash Value Accumulation:
Certain types of life insurance, such as whole life or universal life, offer a cash value component. This means that a portion of your premium payments goes towards building a cash value over time. This cash value can be accessed or borrowed against during your lifetime for various purposes such as supplementing retirement income or funding emergencies.
It’s important to note that the value of life insurance depends on your individual circumstances and financial goals. It’s advisable to consult with a financial advisor or life insurance professional to assess your specific needs and determine the most suitable coverage for you.
Remember, life insurance is primarily a protection tool rather than a traditional investment vehicle. While certain policies may offer cash value accumulation, their primary purpose is to provide financial security for your loved ones.
How do I know how much life insurance I will need?
When it comes to determining how much life insurance you need, there are several factors to consider. Start by assessing your immediate needs, which include any expenses your family would have to cover right away if you were no longer there, such as funeral costs and outstanding debts. Then, look at your ongoing financial obligations. These are the regular, day-to-day living costs that your family will have. If you have children, you’ll also need to think about their future needs, like school fees and college tuition.
Next, consider your future needs, including long-term financial goals. Perhaps you want to leave funds for your spouse’s retirement or an inheritance for your children or grandchildren. Finally, take into account your current assets. These could be savings, investments, retirement funds, or existing life insurance policies. These resources can offset the amount of additional life insurance you may need. Remember, everyone’s situation is unique, so these are just general guidelines. It’s always best to consult with a professional life insurance agent to ensure you’re making the best decision for your specific circumstances.
What is life insurance?
Life insurance is an important form of financial protection that can help provide security for you, your family, and others financially dependent on you in the event of your death. Life insurance is designed to provide a lump-sum payment to beneficiaries (such as a spouse or children) upon the insured’s death. The payment helps cover estate taxes and any other expenses associated with the policyholder’s passing.
What is the difference between life insurance and whole life insurance?
The difference between life insurance and whole life insurance is significant, and understanding the differences can help you decide which type of policy best meets your needs.
Life insurance provides a death benefit to beneficiaries in the event of the insured’s death. It is usually purchased for a limited amount of time (and often called “term” insurance) or can be permanent with no expiration date (whole life). Whole life policies also generally include an investment component that builds cash value over time, allowing policyholders to borrow against that cash value if needed.
What is personal liability insurance?
Personal liability insurance is a type of insurance coverage that helps to protect the individual from being held liable for any financial losses or damages incurred as a result of their actions, negligence, or wrongful behavior. Whether you are an individual or business owner, personal liability insurance can provide you with valuable protection against potential legal and financial costs associated with defending yourself in a lawsuit where you may be found legally responsible for someone else’s injury or property damage.
How does life insurance work?
Life insurance works by providing financial protection to individuals or business owners in the event of their death or disability. The policyholder pays a set premium each month, and upon their death, the life insurance company pays out an agreed-upon sum of money to designated beneficiaries. This allows families to cover final expenses and other costs associated with the loss of someone close without having to dip into savings accounts or use emergency funds.
Why is term life insurance important?
Term life insurance is an important type of life insurance because it provides a significant amount of financial protection for the policyholder or their designated beneficiary. It helps to provide peace of mind by allowing them to know that if something were to happen, their family would have financial security in the form of a death benefit.
With term life insurance, families will not have to worry about shouldering large medical expenses, funeral costs, and other debts left behind after someone passes away. For those who are still working and providing income for their families, having this coverage can also help ensure that household payments can still be made in case the breadwinner is no longer around.
When choosing term life insurance you have control over how long your policy will last; usually between 10-30 years. Depending on your needs and budget you can determine how much coverage you want before deciding what length matches best with your particular situation. As part of this process, it’s advisable to look at such factors as any existing debts or liabilities you may have so that these are appropriately taken into account when determining how much coverage is necessary for yourself or your loved ones should something unforeseen occur while under the policy’s protection.
How does protective life insurance work?
Protective life insurance is a type of permanent life insurance policy that provides a death benefit to the policyholder’s designated beneficiaries upon their passing. This type of policy also accrues a cash value which can be used to supplement retirement income while providing tax-deferred growth potential.
Protective life insurance works similarly to other types of permanent, whole, or universal life policies in that it has two primary components – the death benefit and the cash value accumulation portion. The death benefit provides coverage for beneficiaries and remains constant throughout your lifetime as long as you pay enough premiums to keep your policy in force. The cash value component allows you to accumulate funds in an account within your policy that earns modest interest rates over time, allowing you and/or your beneficiaries access to those funds for supplemental retirement income or other financial needs during life if needed, all without incurring current taxes on those withdrawals.
In order for protective life insurance policies to remain active (and thus provide both the promised death benefits as well as grow their associated cash values), they require premium payments at regular intervals. It’s important to understand these payment schedules before signing up for any such plan; not making premium payments on time could result in forfeiture of any accrued benefits – so make sure you read through all the details with any particular plan before committing!
Why us
Are you ready to take control of your financial future?
Contact Denis Doulgeropoulos today and start your journey towards financial success!